

A reader asks:
I’m 44. I lived through the Dot-com bust and 2008, which just taught me to be a machine. I don’t get defensive; I just relentlessly dollar-cost average. My secret to staying the course has been reading financial books to keep my head on straight.
Thanks to two decades of DCA, compounding is really doing the heavy lifting. But it’s a psychological toll. A standard 10% correction now means a dollar swing larger than my annual salary. Even with a stoic mindset, seeing a house-sized amount of money vanish on a screen feels heavy.
My question: How do you mentally handle the shift from early accumulation to the “mid-life compounding phase”? How do I maintain my robotic DCA mindset when the absolute dollar swings become this staggering? Thanks for keeping me sane, and congrats on the new book!
I love this question because it shows how there is a natural lifecycle for investors.
Risk means different things to different investors at different stages of life.
Middle-aged people are the Gen X of the financial advice world — completely ignored and overlooked.
There is plenty of financial advice out there for young people on how to save, invest, pay down debt, plan for the future, etc. That’s when developing prudent personal finance habits matters the most.
There’s also all kinds of financial advice for retirees in terms of tax planning, portfolio withdrawal strategies, asset allocation studies and such.
There isn’t a lot of oxygen devoted to people in the mid life crisis stage of life. You could argue this is the point where financial planning is the trickiest.
You have a foot in both camps.
On the one hand, you still have some time to save and invest. Plus, you should be at the point in your career where you are maxing out your income.
But you also have more responsibilities — kids, saving for college, taking care of your elderly parents, etc. It’s the sandwich generation. Plus, you should have more financial assets at this stage in your life as your portfolio is more mature.
If you’re been diligently saving and investing over the years, that means you have a lot more money at stake when things go wrong in the markets. The dollar losses will sting far more.
If you’re in your 20s with $15k in retirement savings and the stocks market crashes 50%, you can make your portfolio whole with one year of Roth IRA contributions.
If you have a $1 million portfolio, a 10% decline in the stock market wipes out more than the median household income in the United States.
I am in the same camp as our dear reader asking this question. I sat through the lost decade of the 2000s. I was perfectly fine shoveling money into my 401k during the Great Financial Crisis, mainly because I didn’t have a ton of money at the time. I’ve also been a dollar cost averaging machine for the past 20+ years.
The fact that this bull market has been so strong means I now have way more at stake than I did earlier in my investing lifecycle.
Here’s the biggest question you have to ask yourself as a middle-aged investor: Does a change in your lifecycle require a change in strategy or a change in mindset?
One of the biggest lessons I’ve learned working in wealth management all these years is that portfolio changes in client accounts happen more frequently from life events rather than market events.
A marriage, birth, death, inheritance, windfall, career change, retirement, etc. Sure, markets can sometimes force your hand by changing the risk-reward set-up for an asset class, but it’s typically life circumstances that leads to a change in investment strategy.
An investing midlife crisis is one of the main reasons many people begin a retirement glidepath by slowly but surely selling risk assets to buy assets with less volatility. Maybe you take a 100% equity portfolio and sell 3-5% per year until you reach a new steady state of an 80/20 or 75/25 portfolio where the 20-25% is in bonds, cash or some other income-producing asset.
This is what targetdate funds do as you get closer to retirement age.
That would mean lower expected returns but it can also help reduce emotional volatility when the stock market falls out of bed. It might help you sleep better at night to know a larger chunk of your portfolio is now in assets with less short-run volatility.
The other option is to re-frame the denominator. Don’t think about your portfolio in terms of dollar amounts but rather compounding terms.
I wrote a blog post a long time ago about the relationship between saving and investing. Using some simple retirement calculator assumptions1 I wanted to look at how the ending portfolio value evolves over time from contributions to investment gains.
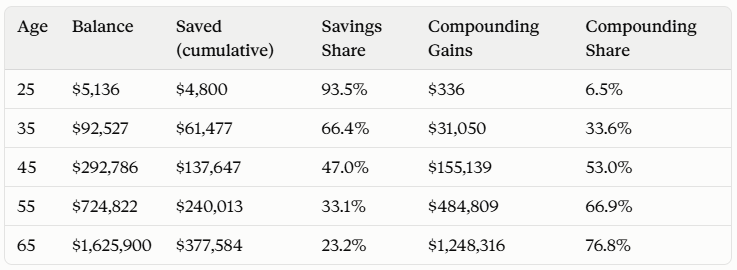
How much you save has a far greater impact than your investments early on in your career. But as your portfolio grows, investment returns swamp your savings because of the wonders of compounding.
But compounding is back-loaded. Look at how much of your gain in this admittedly unrealistic example come in the last 10 years or so. The snowball really grows biggest at the end when you have more money.
Or course, retirement calculators work in a straight line while the stock market never does.
Do you want to sleep better at night and protect some of your capital?
Or do you want to roll the dice and live with the volatility?
As a fellow middle aged person I’m still risk-on with a barbell portfolio of all stocks in my retirement accounts and cash in my more liquid bucket.
But I have been increasing my allocation to our trend-following strategy because I like having a risk management component based on where I am in life and how strong the stock market has performed this cycle.
There is no right or wrong answer here.
Dealing with an investing mid-life crisis comes down to knowing yourself and what’s going to cause you the most pain and regret.
I covered this question on an all-new Ask the Compound:
We also discussed questions about how to hedge against a government debt crisis, the best asset class to invest in right now, international diversification, where to park short-term savings and how to spend more money in retirement.
Further Reading:
How to Survive Chaotic Markets
1The assumptions are as follows: You start saving 12% of your salary at age 25. You get a 3% raise each year. Your investments grow at 7% annually.
