

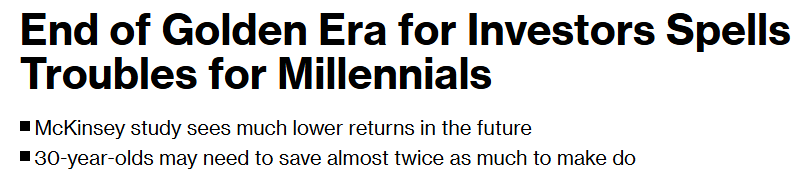
Here’s a story from Bloomberg:
That doesn’t sound good.
Here’s the main argument:
Turning 30 just got a lot scarier.
A coming collapse in investment returns means that people that age today will have to work seven years longer or save almost twice as much to end up with the same nest egg as those of roughly a generation ago.
So says the research arm of McKinsey & Co. in a new report that argues that investors of all ages need to resign themselves to diminished gains.
The consulting company maintains that the last 30 years have been a “golden era” of exceptional inflation-adjusted returns thanks to a confluence of factors that won’t be repeated. They include falling inflation and interest rates, swelling corporate profits and an expanding price-earnings ratio in the stock market.
The next two decades won’t be nearly as lucrative, even on the optimistic assumption that the world economy snaps out of its recent funk and resumes growing at a faster clip.
A lot of investors probably feel the same way.
Here’s the problem — this story was originally published in 2016. I wrote about it at the time — Are Millennials Doomed in a Lower Return Environment?
These were the forecasts from McKinsey from the report:
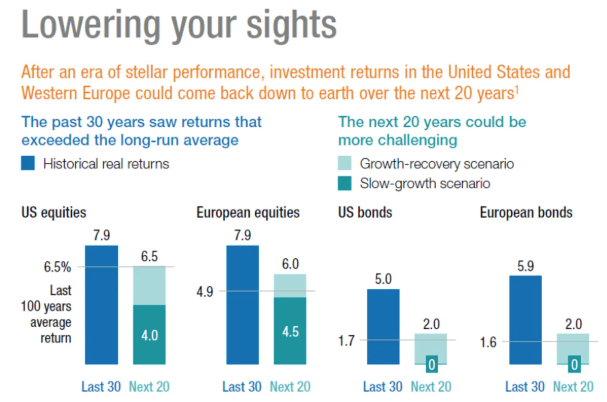
We’re now past the halfway point for these 20 year forecasts.
Since this was published the U.S. stock market is up well over 300% in total or 15% per year:
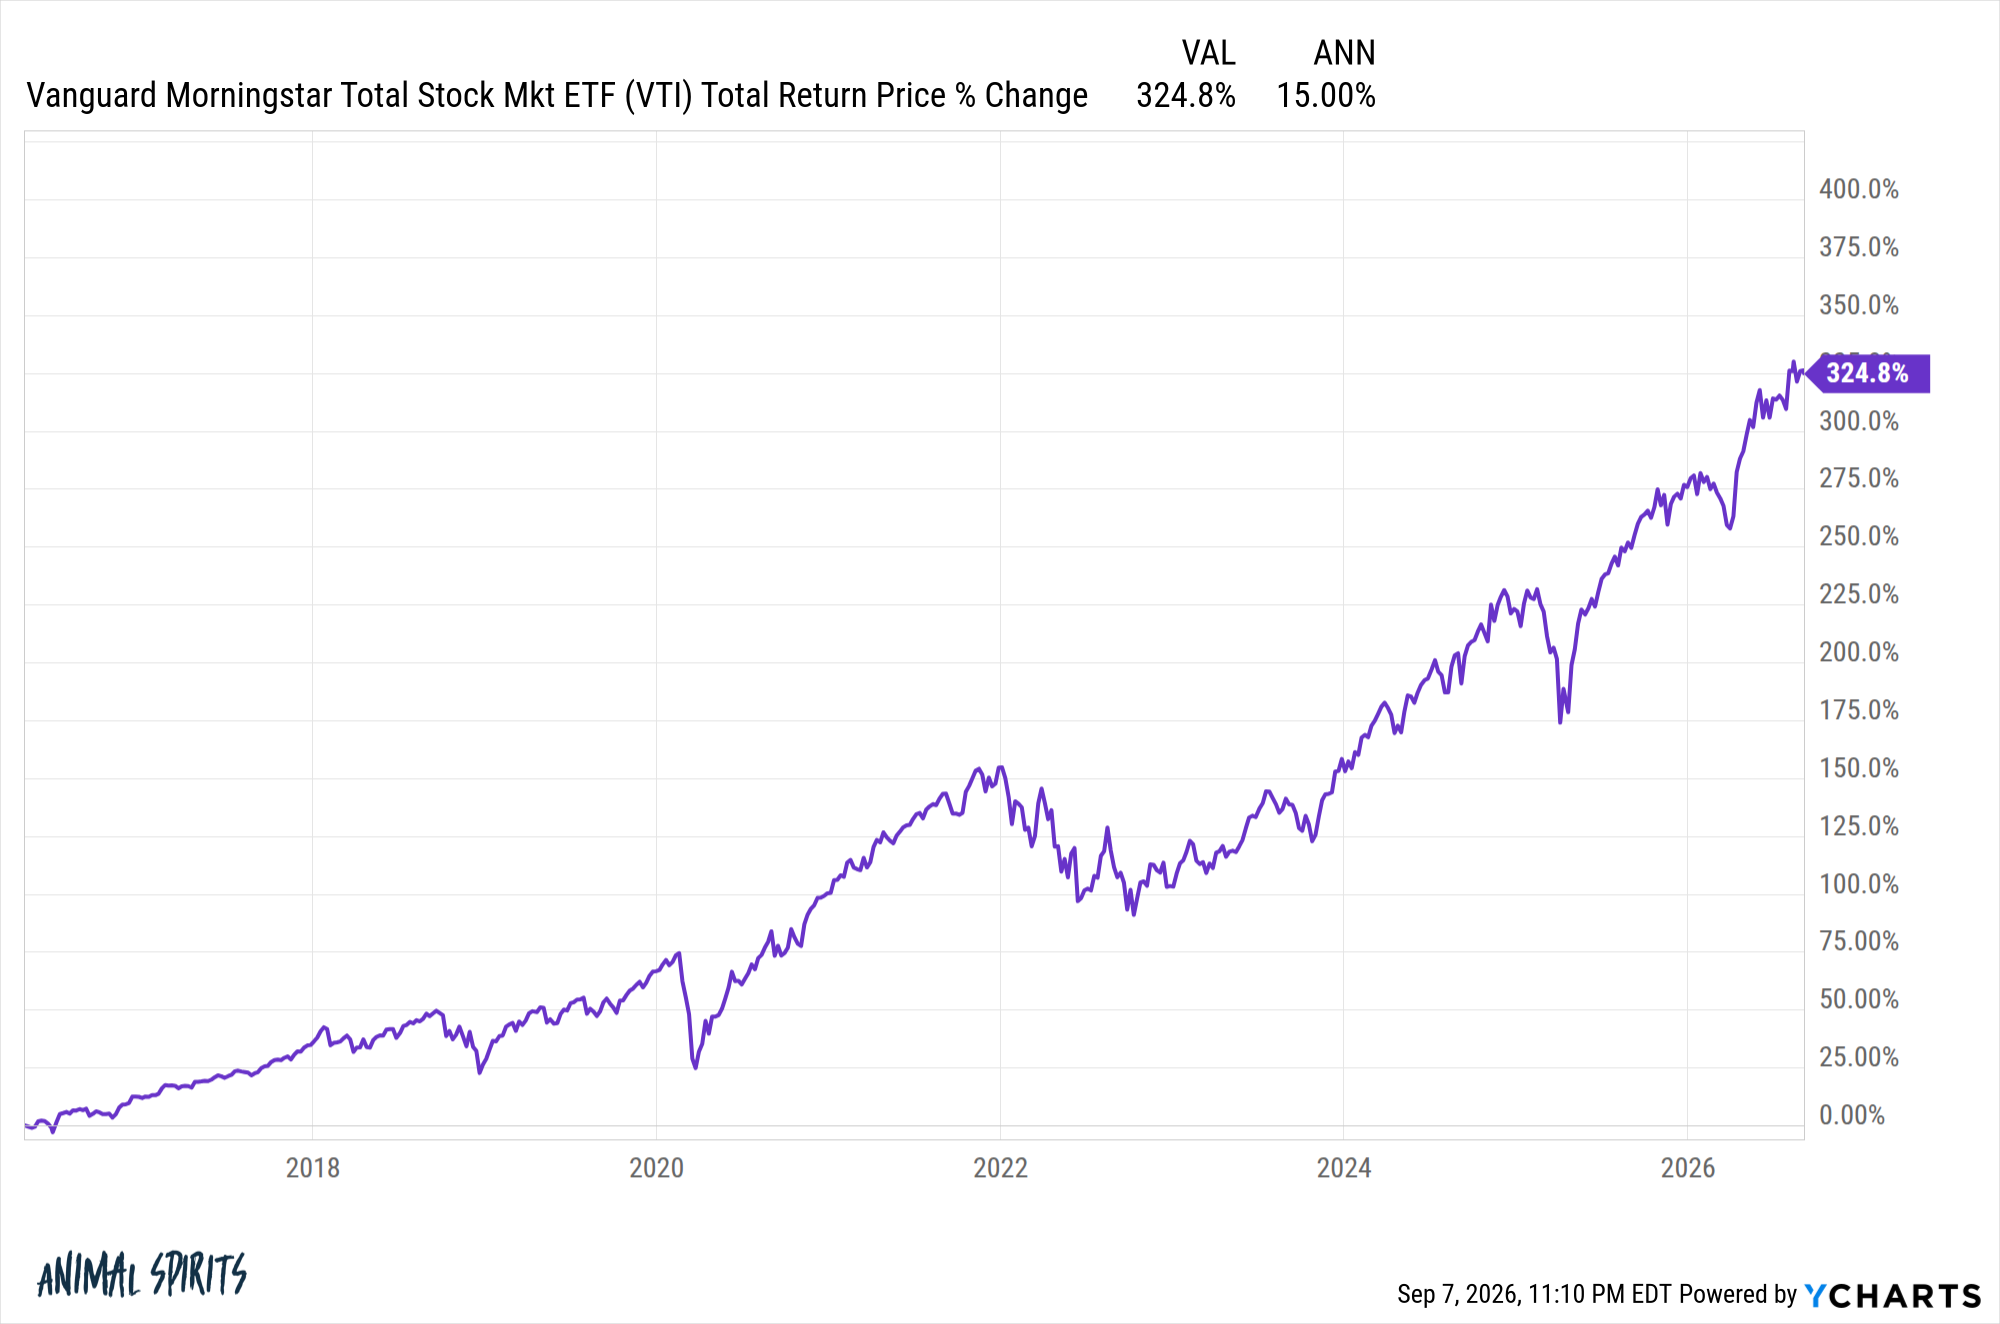
Inflation over the past 10 years was running at an annual rate of 3.3%. That’s a real annual return of 11.7%. So the past 10 years have experienced higher real returns than the “Golden Era” for investors in the 30 years ending in 2015.
Even European stocks, which haven’t exactly been lighting the world on fire this cycle, were up almost 10% per year since the spring of 2016.1
I think it’s important to take a look at old forecasts as a reminder about how hard it is to predict the future of the markets.
In May of 2010, Seth Klarman told The Wall Street Journal he was more worried than ever before in his career: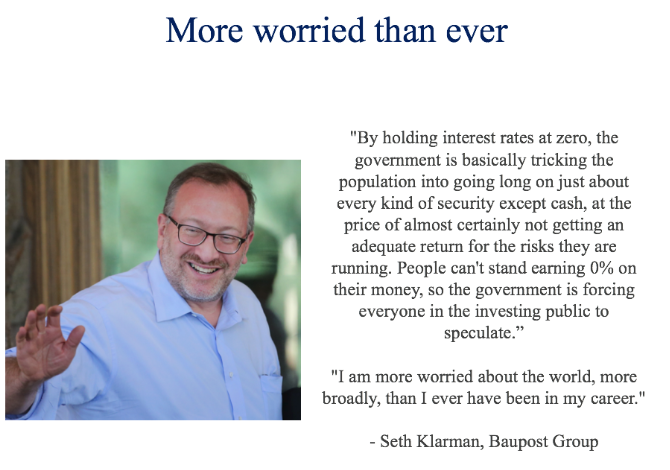
U.S. stocks are up more than 800% since he shared these concerns. That’s almost 15% per year.
In May 0f 2020, Stanley Druckenmiller told the crowd at The Economic Club of New York that, “The risk-reward for equity is maybe as bad as I’ve seen it in my career.”
The stock market is up almost 200% from those levels, compounding at an annual rate of nearly 18% per year.
Everyone assumed a recession was a foregone after inflation spiked in 2022:
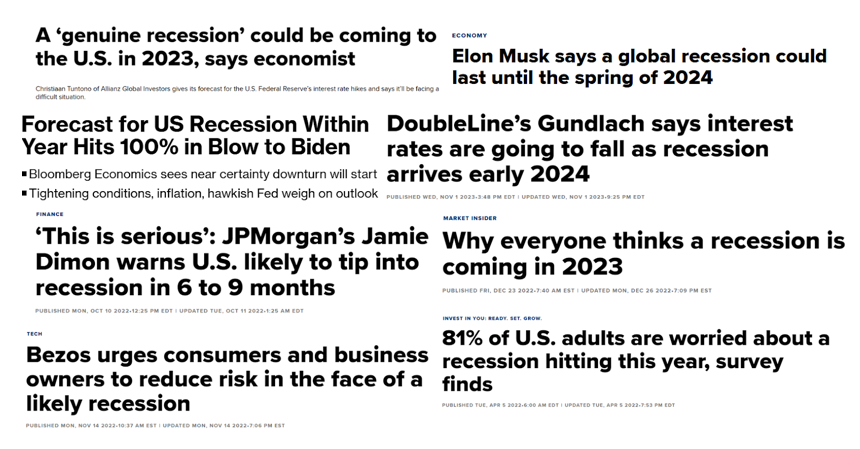
It didn’t happen. The economy continues to grow.
I’m not saying you should ignore risks and market warnings always and forever. This cycle will turn at some point. Investors will pivot from risk on to risk off. Stocks will go down. We will have a recession.
I just don’t think anyone has the ability to predict when that will happen.
I know it’s unsatisfying to hear that even the consultants, billionaires and legendary investors don’t know what’s going to happen next but it’s the truth.
Sometimes the three most important words for investors are: I don’t know.
I don’t know when this bull market will end.
I don’t know if AI will lead to a utopia where everything is better or a hellscape where the robots steal everyone’s job.
I don’t know if the economy will expand for the rest of this decade or go into a recession next year.
I don’t know if the new Tom Cruise movie will be a ridiculous flop or a revelation that gets TC his first Oscar.
I don’t know if the AI capex binge will lead to enormous returns for the hyperscalers or a huge crash.
Life — and investing — would be a whole lot easier if there were a group of soothsayers who could tell us all what’s going to happen next.
Nobody knows what’s coming next.
That inherent uncertainty provides both risk and opportunity.
The biggest risk is thinking you’ve found a guru who can tell you what will happen on a consistent basis.
That person does not exist.
Further Reading:
No One Knows What Will Happen
1To be fair to McKinsey’s report, bond returns have stunk in the past 10 years. The annual return for the Agg was 1.5% per year, meaning bonds lost money to inflation.
