

Edward Chancellor’s The Price of Time provides a wonderful explanation of the importance of interest rates in a functioning economic system.
Interest rates help determine how we value money today versus money in the future.
Interest rates shape how businesses and households think about saving, investing, borrowing and taking on risk.
Chancellor does a better job than I could at explaining why rates are so important in creating the time value of money:
The most encompassing view of interest is contained in the notion of interest as the ‘time value of money’ or, simply, as the price of time.
From a technical viewpoint, capital consists of a stream of future income discounted to its present value. Without interest, there can be no capital. Without capital, no capitalism.
Chancellor spends much of the book railing against the period of low interest rates that came out of the Great Financial Crisis. He argues that ultra-low interest rates are dangerous because they encourage excessive risk-taking, punish savers, distort the price of time, inflate asset prices, prop up zombie companies and in many ways weaken the economy.
There were a lot of economists and prognosticators who railed against the zero interest rate policies (ZIRP) in the 2010s. Many thought it would lead to a crisis. There were fears of hyperinflation, a crash in the dollar and excessive speculation.
What’s strange to me is that ZIRP didn’t really lead to any of those things. Sure, asset prices went higher but that’s mostly because the stock market went through a lost decade in the 2000s and the behemoth tech companies stepped in to save the day by providing actual profits.
Interest rates have been higher this decade but the S&P 500 in the 2020s has actually outperformed the 2010s. So you can’t say it was all low rates propping up the stock market. Stocks have been booming with 4-5% rates for a number of years now.
There is always something to complain about regardless of the interest rate environment.
When rates are low — the Fed is punishing savers!
When rates are high — the Fed is punishing borrowers!
There is a lot more than goes into market-related decisions than the level of interest rates.
Mortgage rates were low for the majority of the 2010s but we didn’t get an actual housing market boom until the pandemic forced people to reassess their living situation by being cooped up in their house.
The 10 year Treasury yield averaged more than 10% throughout the 1980s yet the stock market went wild. Bond yields were more than 5-6% for much of the dot-com bubble. Investors don’t care much about yields when the stock market is booming.1
The big thing you need to understand is that there is no such thing as a “normal” rate of interest. Take a look at historical yields on the 10 year going back to 1940:
Interest rates are basically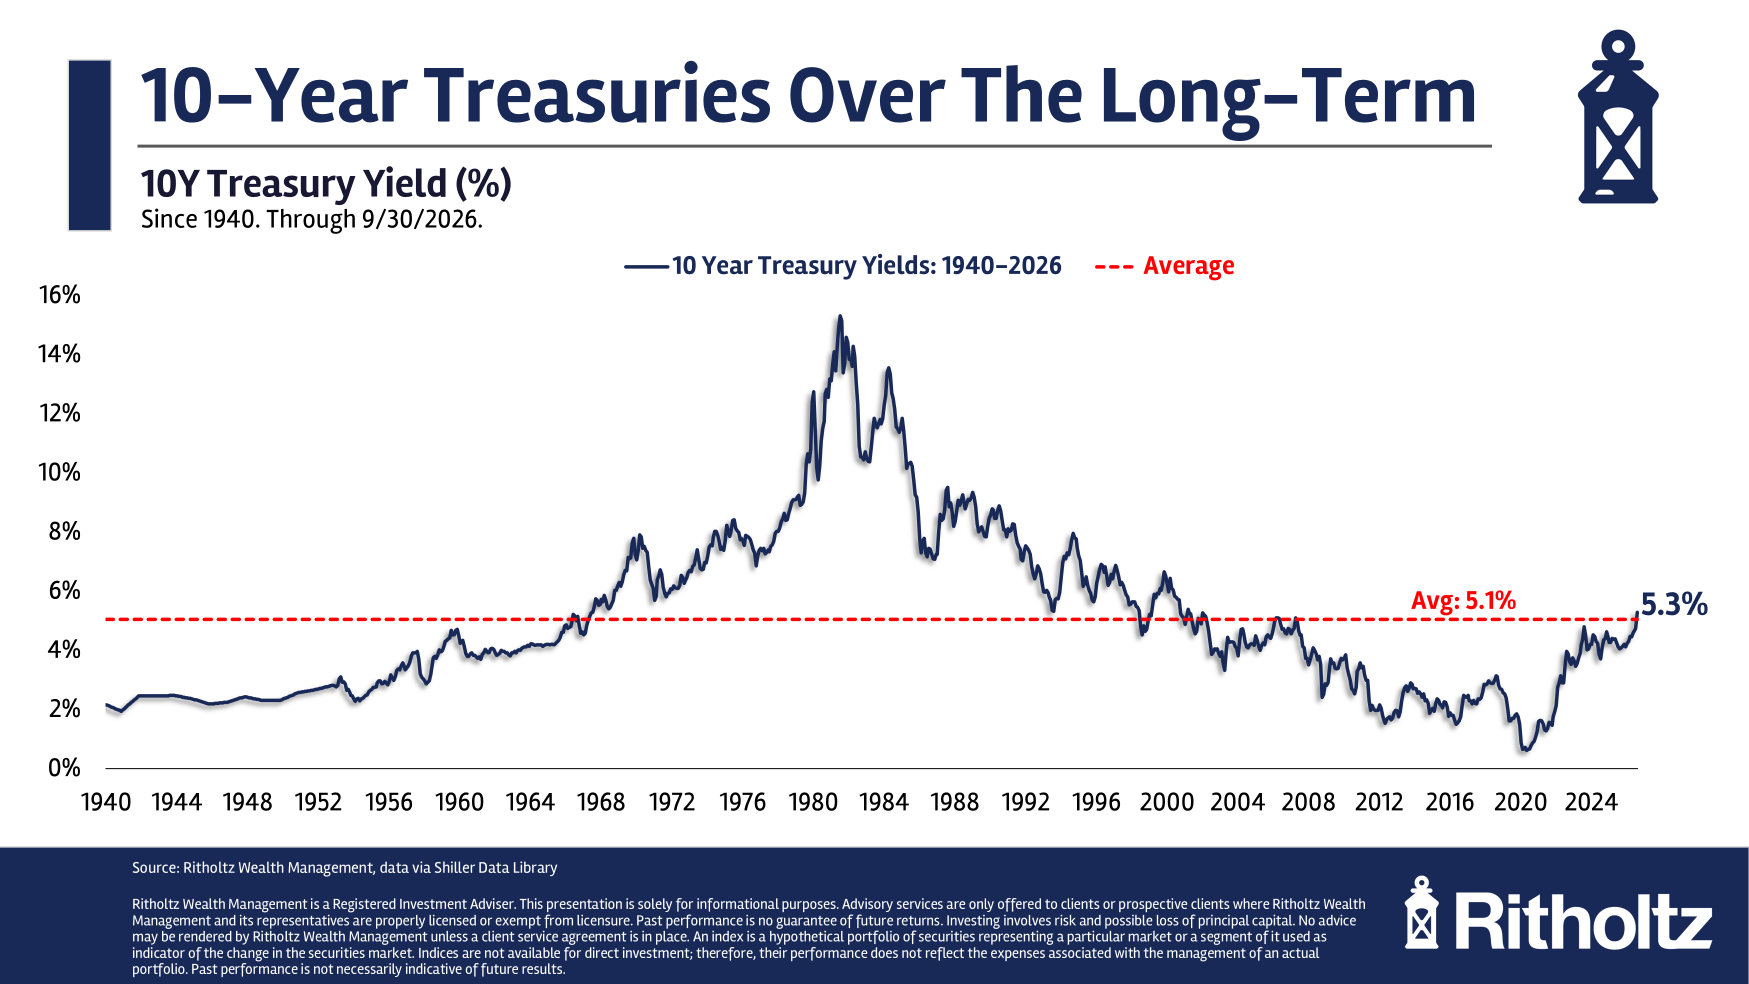 never normal.
You had a period of suppressed rates during WWII when the government kept a lid on yields to fund the war.
Then interest rates rose from the 1950s to the early 1980s as inflation came roaring back.
From there we had four decades of disinflation and falling interest rates.
That ended with bond yields on the floor during the pandemic.
Ever since then we’ve once again been in a period of rapidly rising bond yields with higher inflation.
And while ZIRP didn’t cause a crisis in the way many prognosticators thought, what it did was leave zero margin for safety when it came time to finally raise interest rates.
For example, a 7.5% 30 year mortgage rate isn’t out of the norm historically. Mortgage rates never once went lower than 9% in the 1980s. The average rate in the 1990s was more than 8%.
But housing prices in the 2020s were used to a world of 3-4% mortgages. Today you have 7.5% mortgage rates with housing prices that only work with 3% rates.
The combination of unaffordability and homeowners with 3% mortgages who refuse to move has resulted in a situation where housing market activity has been nuked. And it’s probably worse than you think.
Here I’ve charted existing home sales and U.S. population growth this century:
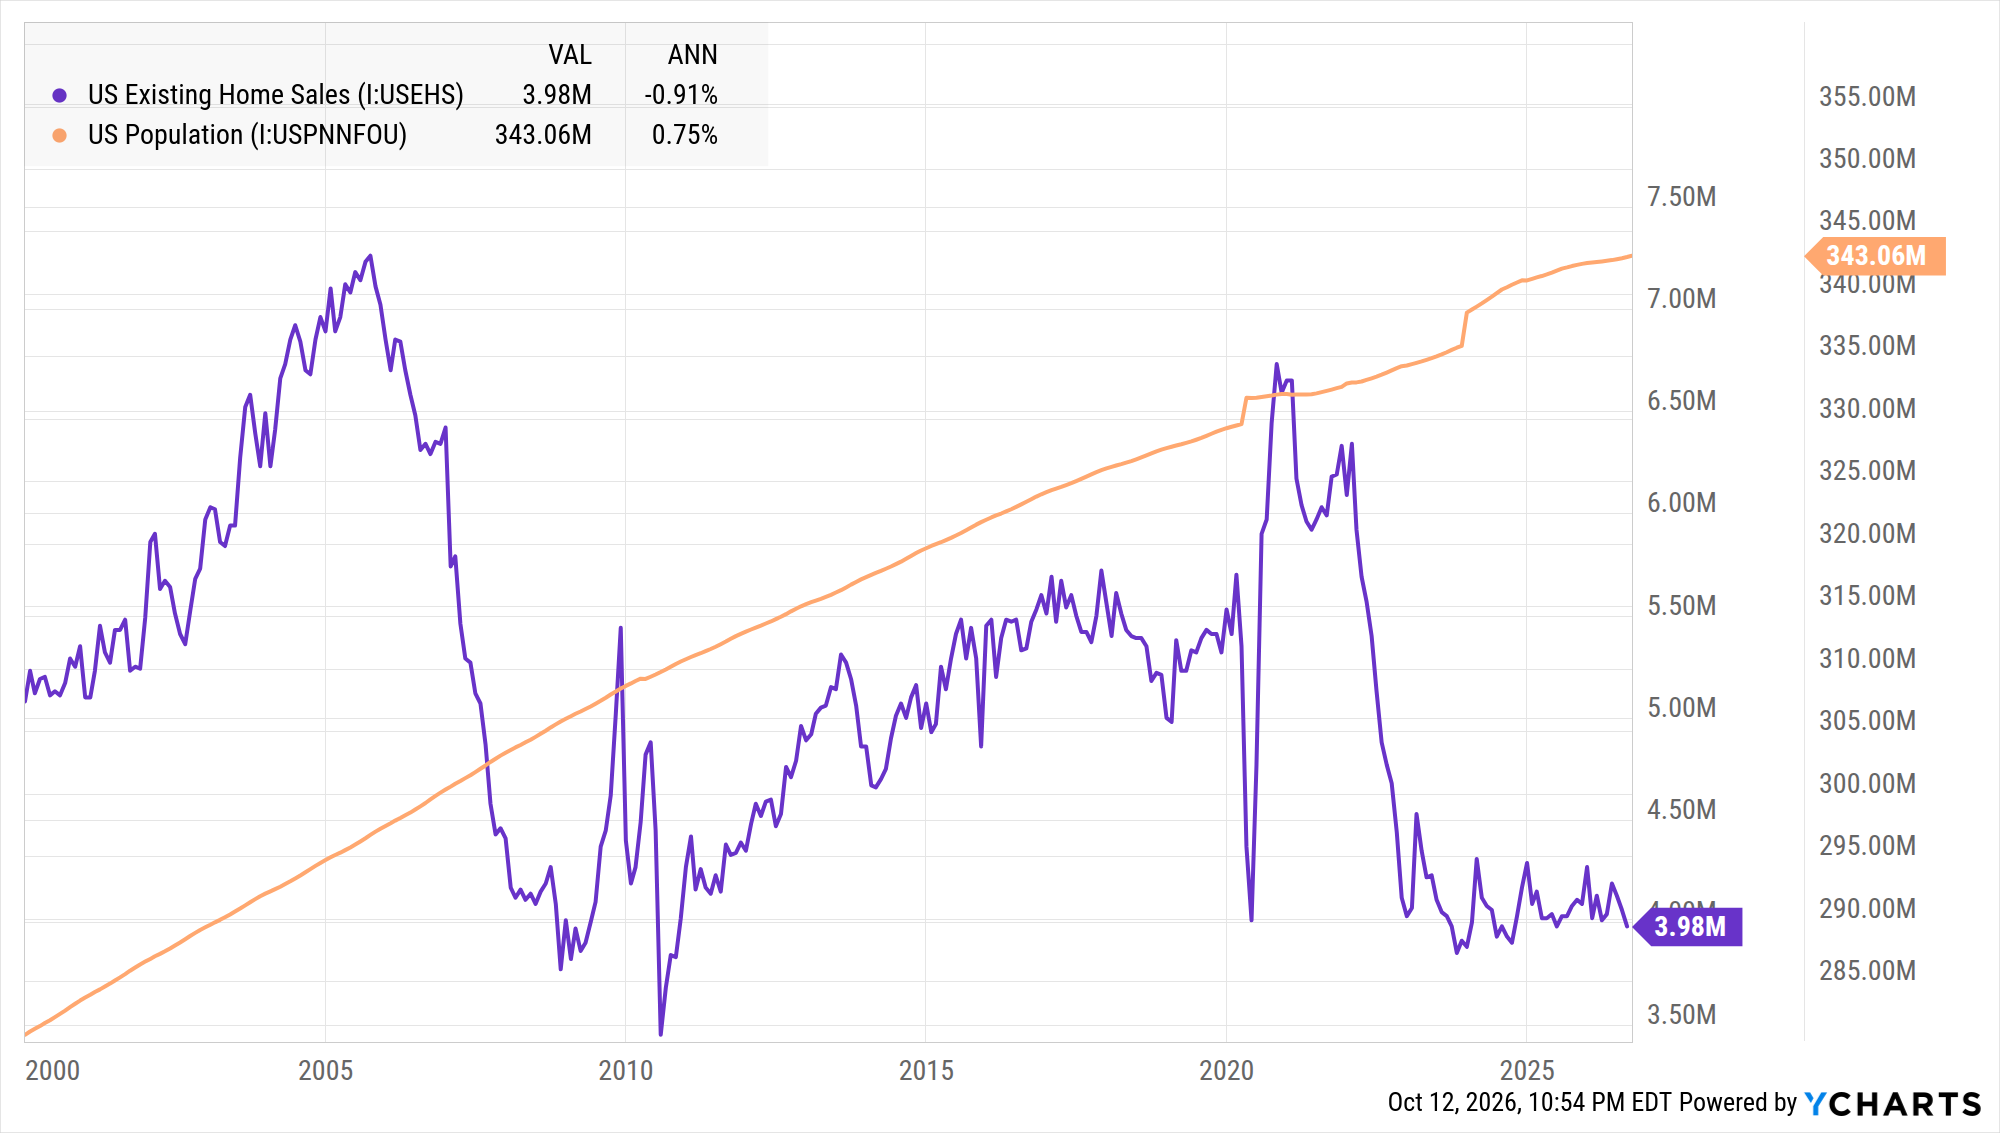
In 2000, you had more than 5 million homes changing hands a year. Today it’s just shy of 4 million existing home sales. But back then we were a country with 280 million people and 105 million households.
Today you have more than 340 million people and 135 million households.
If you adjust sales activity for population you can see how bad the past few years have been:
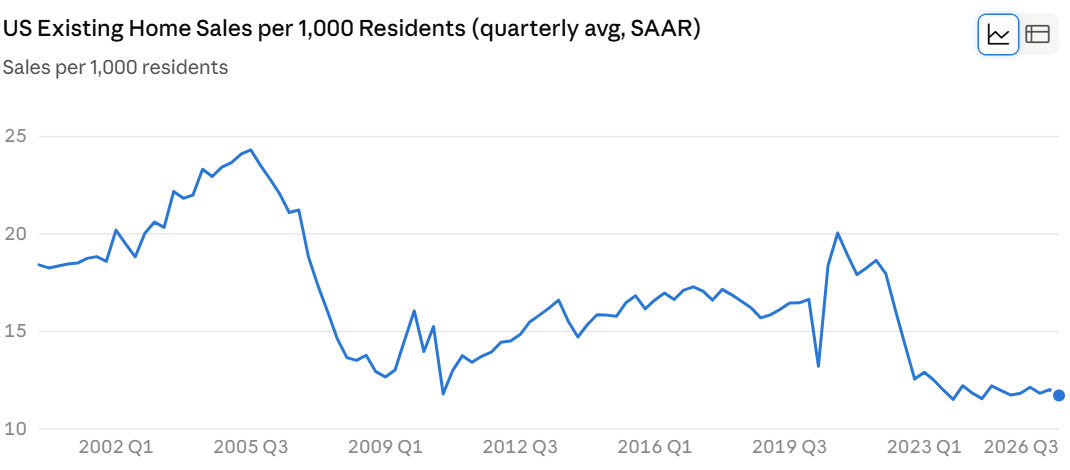
We’ve now been stuck with lower existing home sales than the bottom of the housing bust for three years.
This has been a brutal time to be a potential homebuyer.
Plus, housing activity plays a huge role in the economy. John Burns has a chart that show housing makes up roughly 20% of economic activity:
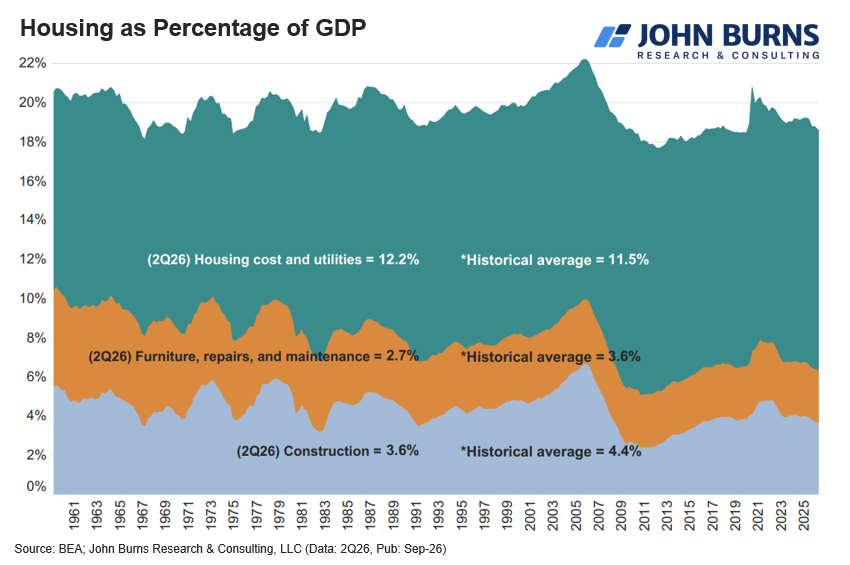
Going from very low interest rates to much higher rates has neutered this enormous part of the economy.
I’m not saying ZIRP was better than what we have today. I am saying I don’t think policymakers have thought about what it means to go from one extreme to the next when it comes to interest rates.
There is no such thing as normal when it comes to interest rates.
But I don’t think we’ve been very thoughtful about how damaging it’s been for certain households and parts of the economy when it comes to such big moves in rates in such a short period of time.
Michael and I talked about the impact of higher interest rates, ZIRP and more on this week’s Animal Spirits video:
Subscribe to The Compound so you never miss an episode.
Further Reading:
The Winners & Losers of Higher Interest Rates
Now here’s what I’ve been reading lately:
Books:
Podcast book tour:
1Yields begin to matter a lot more when the stock market is going down.
