

One of the hard parts about financial planning is that you get plenty of at-bats at the little stuff, like spending money, investing, and saving, but not a lot of opportunities to practice the big stuff.
You might get a few chances at choosing a home, taking out a mortgage or finding the right career path.
When it comes to retirement, short of reincarnation, you get exactly one shot at it. Retirement is trial by fire.
This is what makes the entire process so nerve-wracking.
What if inflation is higher than expected?
What if returns are lower than expected?
What if you retire right before a brutal bear market?
What if you outlive your money?
Some people have better timing than others.
Today feels like a wonderful time to retire. Confidence is running high.
We’ve had a booming stock market. Housing prices are up a ton. Anyone who has held risk assets in this cycle should be doing much better than expected because returns have been above average across the board.
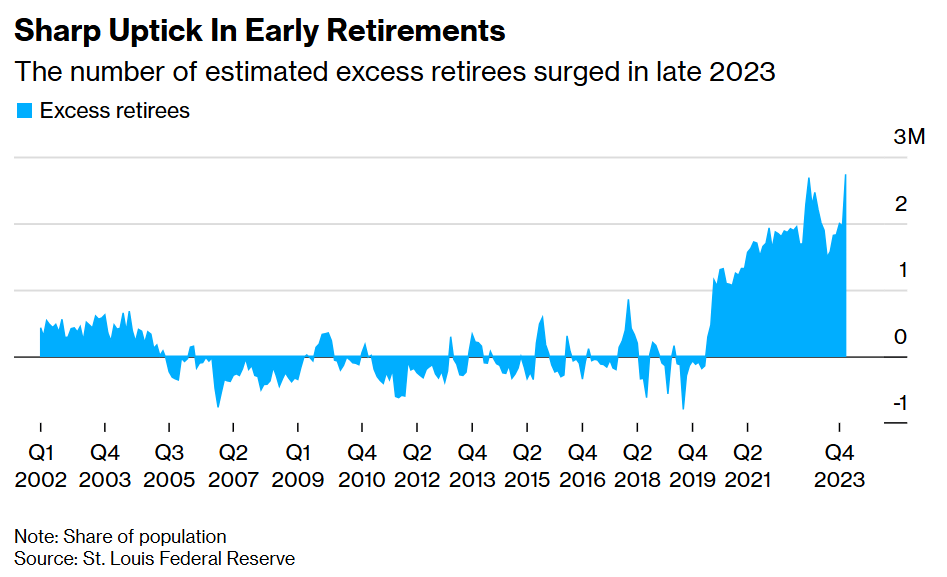
A lot of people have been retiring earlier because of this. Bloomberg has a good chart that shows a big uptick in early retirements this decade:
No one wants to retire in a bear market.
Lots of people want to retire in a bull market.
Christine Benz shared an interesting study on this phenomenon:
But the same forces that have fueled retirement confidence have the potential to work against new retirees in the years ahead. A 2012 study conducted by researchers at the University of Missouri found that workers often retire when the market is cresting. Somewhat counterintuitively, that has the effect of reducing a portfolio’s durability, unless the new retiree steers most of their assets out of the market and into an annuity.
People feel better about retiring when markets are booming and portfolio values are high. When markets are booming and portfolio values are high that can often be following by a bear market or lower returns.
That can increase sequence of return risk which is the idea that poor returns at the outset of retirement can do lasting damage to your portfolio if you sell things that are down.
The confidence you get from above average market returns can actually leave you exposed to other risks.
Of course, you always have a nagging suspicion in the back of your mind that the worst possible outcome will occur after you make a big financial decision.
You don’t get to choose what happens to the markets or economy after you retire.
And retirement is longer than ever before. For many retirees, that could mean 20 to 30+ years of managing your assets in retirement.
You will deal with corrections, bear markets, and a whole host of different economic environments.
I know a couple who retired in March of 2000 at the peak of the dot-com bubble. From that peak, the stock market fell by half in one of the longest bear markets in history.
After stock prices recovered a few years later when the Great Financial Crisis saw the market dive nearly 60%. The stock market went nowhere for the entire first decade of their retirement.
What a nightmare.
Yet they survived through some combination of diversification, cash management, intelligent rebalancing and flexibility. But the biggest thing they had was a plan they could follow that took into account a wide range of scenarios, even really bad ones.
I don’t know if now is one of the worst times to retire but risk assets are up a lot. More people are retiring than ever. Confidence is and should be at all-time highs just like portfolio values.
It’s a good idea to stress test your retirement plan and have some contingencies in place just in case.
Christine joined me on Talking Wealth this week to discuss retiring after a historic bull market, sequence of return risk, retirement withdrawal strategies, bucketing, the 10 year retirement plan, the 4 year spending rule and much more:
Or listen to the podcast version here:
Further Reading:
The 4 Year Rule for Retirement Spending
