

A reader asks:
I’m a late-20s CPA. Married, no kids yet. I’m admittedly a number-crunching spreadsheet guy so let’s leave the psychological components out of this one. On a strictly number basis, is buying a house a terrible investment right now? Mortgage rates are >7%. Home insurance is higher. It takes a lot longer to save for a down payment. Property taxes are higher because housing prices are higher. And housing prices themselves refuse to fall. Compare this situation to the stock market that continues to boom. Bond yields are higher. Option income strategies have double digit yields. Sure we could have an AI bust but isn’t housing the worst financial asset to buy right now? What am I missing?
In the early-2020s when borrowers were still living in those glorious 3% mortgage days, I performed a calculation on the average monthly mortgage payment over the past 30+ years.
I did this using the median U.S. existing home sale price along with the prevailing 30 year fixed rate mortgage level assuming a 20% down payment.
Because mortgage rates were so much lower than they were in the past, the monthly payments weren’t all that much higher from the 1990s or 2000s. That situation changed in a hurry because of the 2020s housing situation.
Prices shot up more than 50% and mortgage rates more than doubled. Look what that did to the average monthly payment:
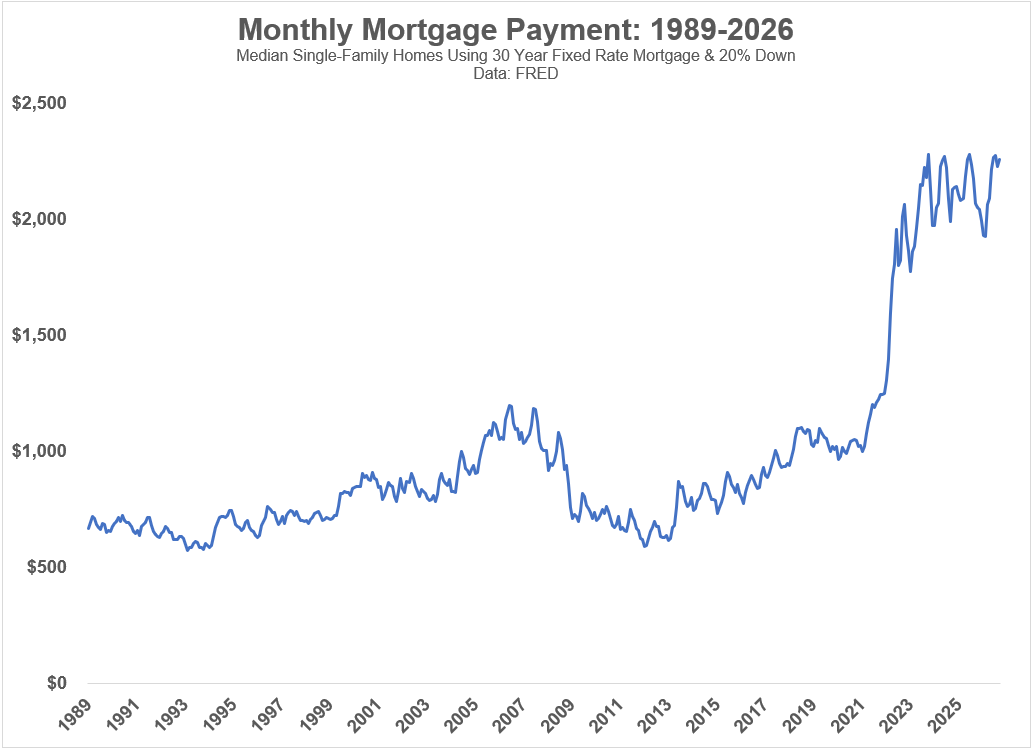
Average monthly mortgage payments have more than doubled from the end of the 2010s.
Add to this the fact that home insurance is up almost 50%, down payments are higher, property taxes are up and you have a situation where affordability is about as bad as it’s ever been.
We also pulled forward a good decade’s worth of gains in the housing market so it would make sense that returns would be lower from here. In fact, home price gains have already leveled off considerably.
This is the Case Shiller National Home Price Index by year in the 2020s: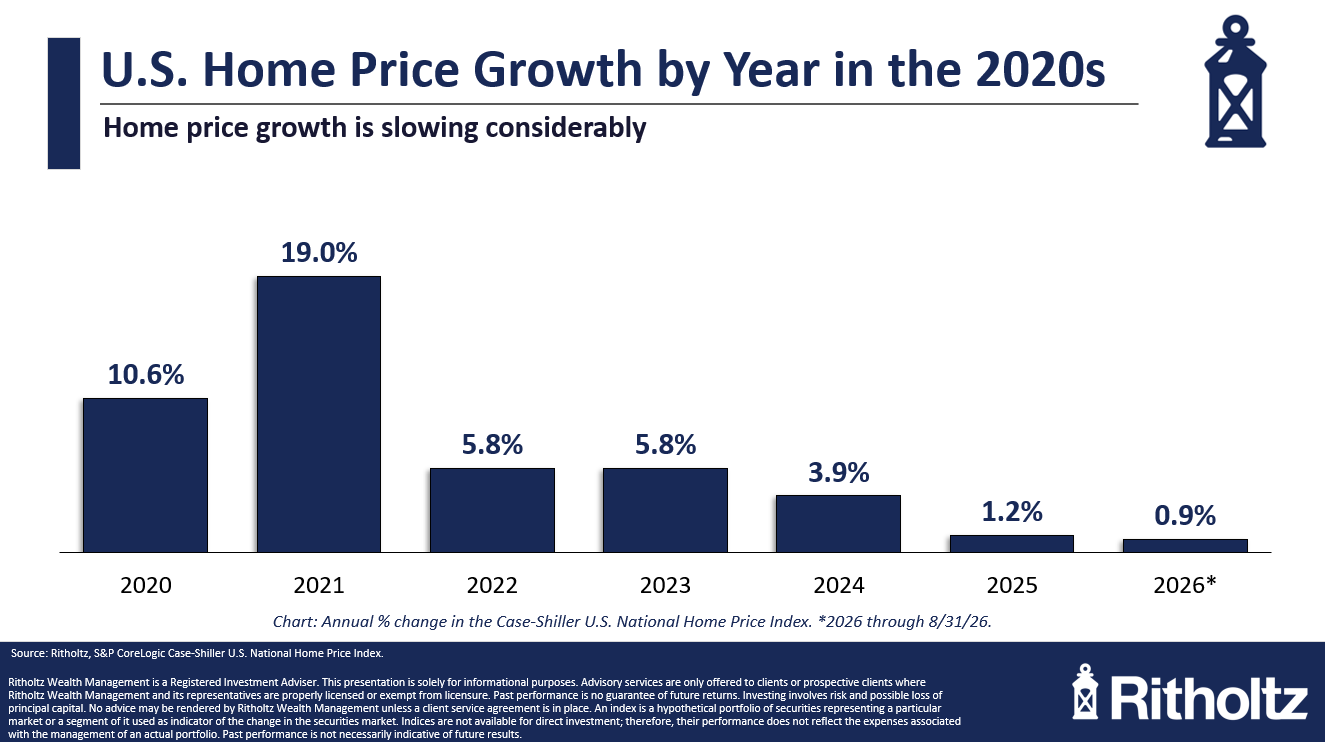
This year is not over but it looks like this will be the second year of muted growth where national home prices grew by less than the inflation rate.
Demographics are still favorable for young people in their home-buying years but the 2030s will likely see a decent amount of supply come to market as baby boomers start dying off, downsizing or moving to Florida.
The bull case for housing is the fact that we simply aren’t building enough houses. There’s also a strong possibility we will experience a surge in housing activity if and when mortgage rates fall to a more reasonable level.1
Obviously, where you buy matters. Some areas will do better than others. Some cities are more unaffordable than others. Some regions are more attractive than others. A lot of it depends on location.
You always have to run the numbers when it comes to renting versus buying. It could be a much better decision financially in some places to rent, invest the difference in the stock market, and not be tied down by the burdens of home ownership.
Or it could make sense to lock in a 30 year fixed rate mortgage, refinance when yields fall and build some equity. You also have to become comfortable owning a concentrated, single, undiversified, leveraged asset.
But I think you’re looking at this the wrong way.
A home can be a financial asset. It can be a store of value as you build equity over time. You can borrow against it if you need to renovate. You can earn some favorable tax treatment.
However, I don’t look at a primary residence as an investment per se. Housing is a form of consumption. You have to live somewhere either way.
Therefore it doesn’t make sense to compare buying a home to the S&P 500. That’s not a realistic benchmark. You can’t live in an index fund. You can’t have your friends over for a dinner party in an ETF.
Plus, the investment expenses on an index fund are straightforward. A home has so many ancillary costs — realtor fees, moving costs, closing costs, property taxes, insurance, maintenance, renovations, lawncare, etc.
Housing is also an illiquid asset. That’s both good and bad depending on how you look at it. It’s essentially a form of forced savings, but it’s difficult to do anything with that savings unless you sell or borrow against your property.
Housing could still be a good investment because of the leverage component. Prices don’t have to rise that much to make a good return on your down payment when you’re borrowing so much money to buy it.
I know you wanted me to leave the psychological stuff out of this but you can’t really.
You buy a home because it’s a place for you and your family to plant roots.
You buy a home because you want some stability in your housing payment and a hedge against inflation.
You buy a home to have more control over your housing situation.
You buy a home to potentially own something free and clear in retirement so someday your biggest monthly expense goes away.
You buy a home to leave something behind to your heirs.
I don’t know if housing will provide solid gains going forward.
If I had to guess, keeping up with inflation would be a good baseline going forward.
But don’t look at buying a home like you would a portfolio holding.
There is so much more that goes into owning a home than owning other financial assets like stocks and bonds.
Run the numbers.
But don’t live and die by the returns you think you can earn on a house.
Housing is more consumption than investment.
Josh came on Ask the Compound with us this week to answer this question:
We also covered questions about directing indexing, why energy stocks are outperforming, why luxury stocks are crashing, how to put cash to work in the market and more.
Further Reading:
Owning a Home is Not For Everyone
1Unless the reason mortgage rates are falling is because we’re living in a financial crisis of course.
