
I’m not much of a contrarian.
By definition, contrarians are wrong most of the time. Fighting the herd only tends to work at the extremes.
Here’s one of my most contrarian opinions right now:
I’m not worried about a U.S. government debt crisis.
We have the world’s largest, most dynamic economy.
We have the biggest, most innovative companies.
We have the most liquid financial markets.
We have the global reserve currency.
We have the most rich people.
There is no substitute for U.S. Treasury bonds at this time.
So my baseline assumption is that people will continue complaining about the trillions of dollars we have in debt but it won’t lead to a financial crisis.
Not many people agree with this take. Most prognosticators assume it’s only a matter of time until our debt burden becomes too large to handle. When debt levels recently hit $40 trillion the outrage was off the charts.
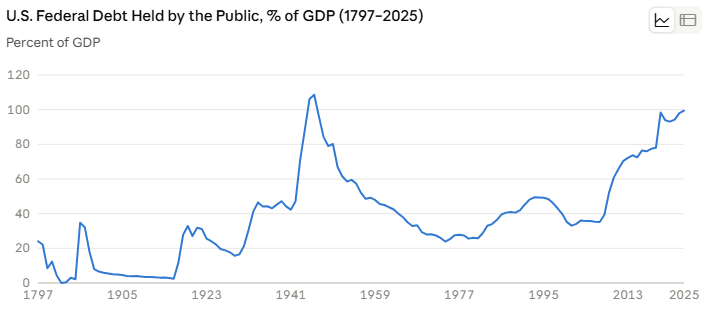
I understand why people are worried right now. Here’s debt-to-GDP going way, way back:
The only other time it was higher is World War II.
Now look at the interest expense as a percentage of GDP:
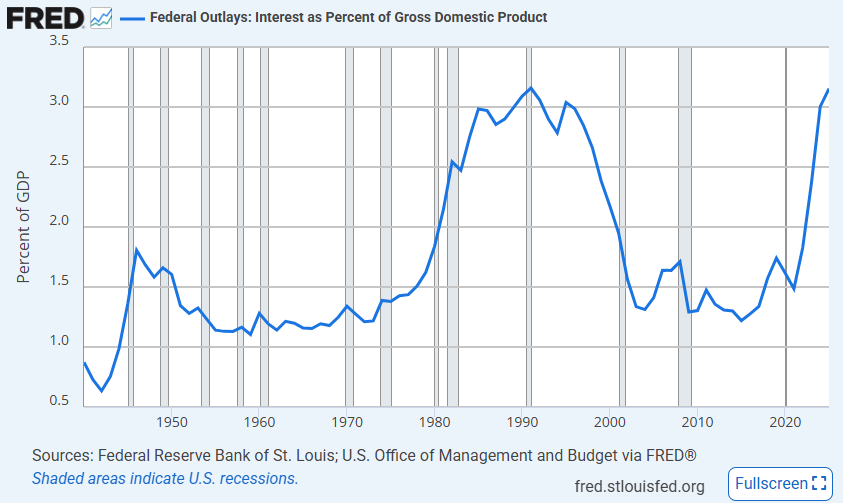
It’s skyrocketed along with interest rates and government debt in the 2020s.
It certainly feels like nothing stops this train. For my entire adult life I’ve been told taxes have nowhere to go but up. Yet we keep getting tax cuts and no one on either side of the aisle is making proposals to lower the deficit.
The worry is that our interest expense becomes such a large part of the budget that difficult choices will have to be made.
I’m not saying there aren’t potential problems with ever-increasing government debt. There could be. But let’s look at some positives, yes, positives of all this spending.
A combination of spending to combat the Great Financial Crisis, the pandemic and loads of tax cuts has allowed Americans to repair their household balance sheets.
Morgan Housel shared the following chart which shows both government and household debt as a percentage of GDP:
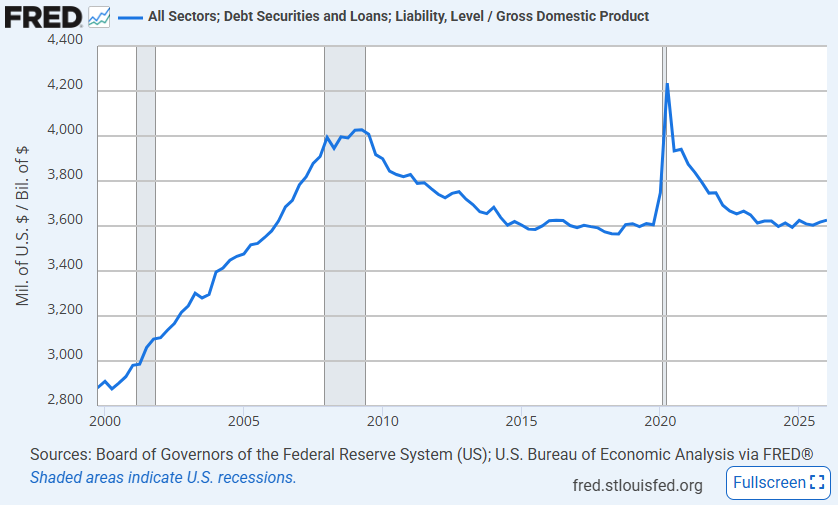
The level is unchanged over 20 years. While government debt has exploded higher, household balance sheets are in a much better place after getting to unhealthy levels heading into the 2008 debacle.
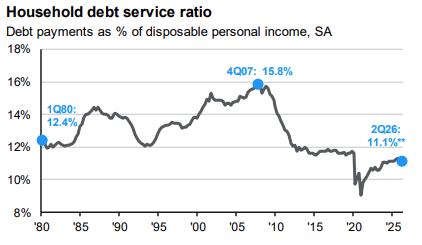
Look at these charts from JP Morgan that show households debt service ratio falling off a cliff since the GFC:
And look at consumer assets versus liabilities:
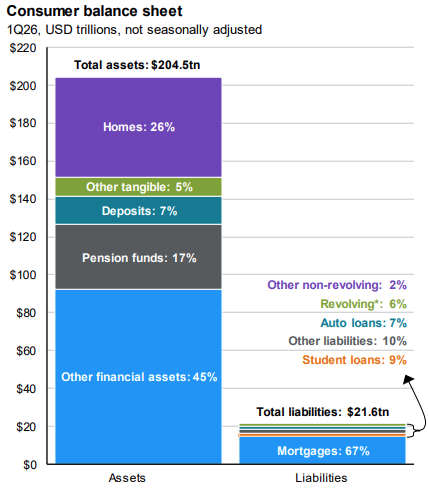
It’s not even close.
Cullen Roche wrote about the asset side of the equation recently:
The US government’s debt passed $40 trillion this week. That is a humongous number. Did you know that total US financial assets are almost $450 trillion? If you include non-financial assets you’re getting close to $600 trillion. So yes, the US government is huge, but it’s just huge inside of another yuger thing (misspelling intended!).
Had the government showed more fiscal restraint in the past 15-20 years we could be looking at a pristine government balance sheet while household finances are a mess.
Is that a trade-off you would be willing to make? I think the fact that the government took on debt during two crises to help households was a good trade-off.
Now, I’m not saying all of the government spending has been necessary. We’ve spent an inordinate amount of money on wars and tax breaks for the rich this century. And I’m not here to claim there are no risks from current government debt levels.
I just don’t think we are at risk of a financial crisis.
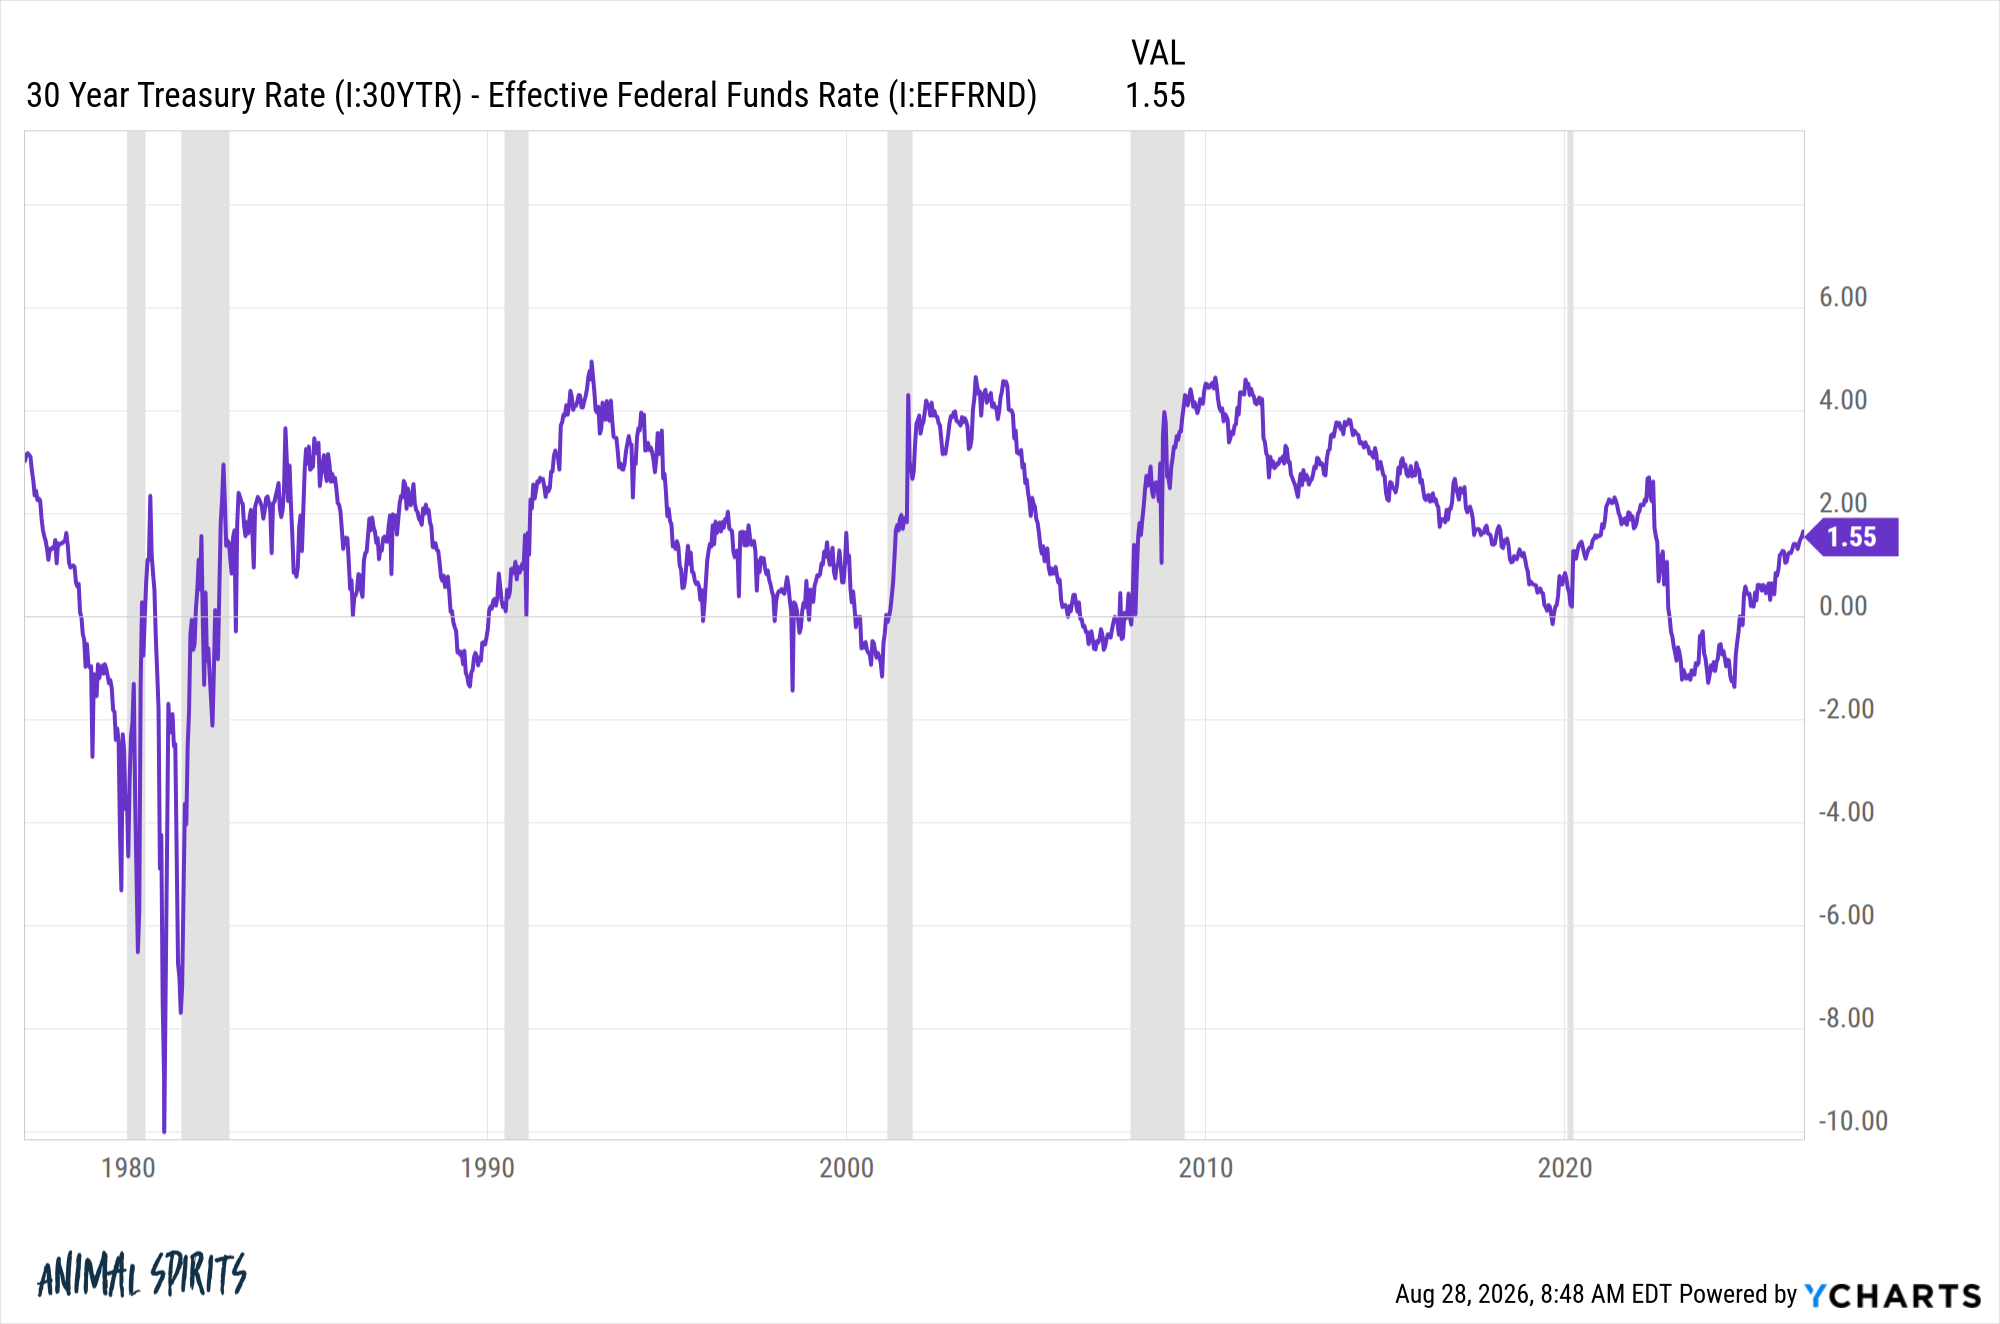
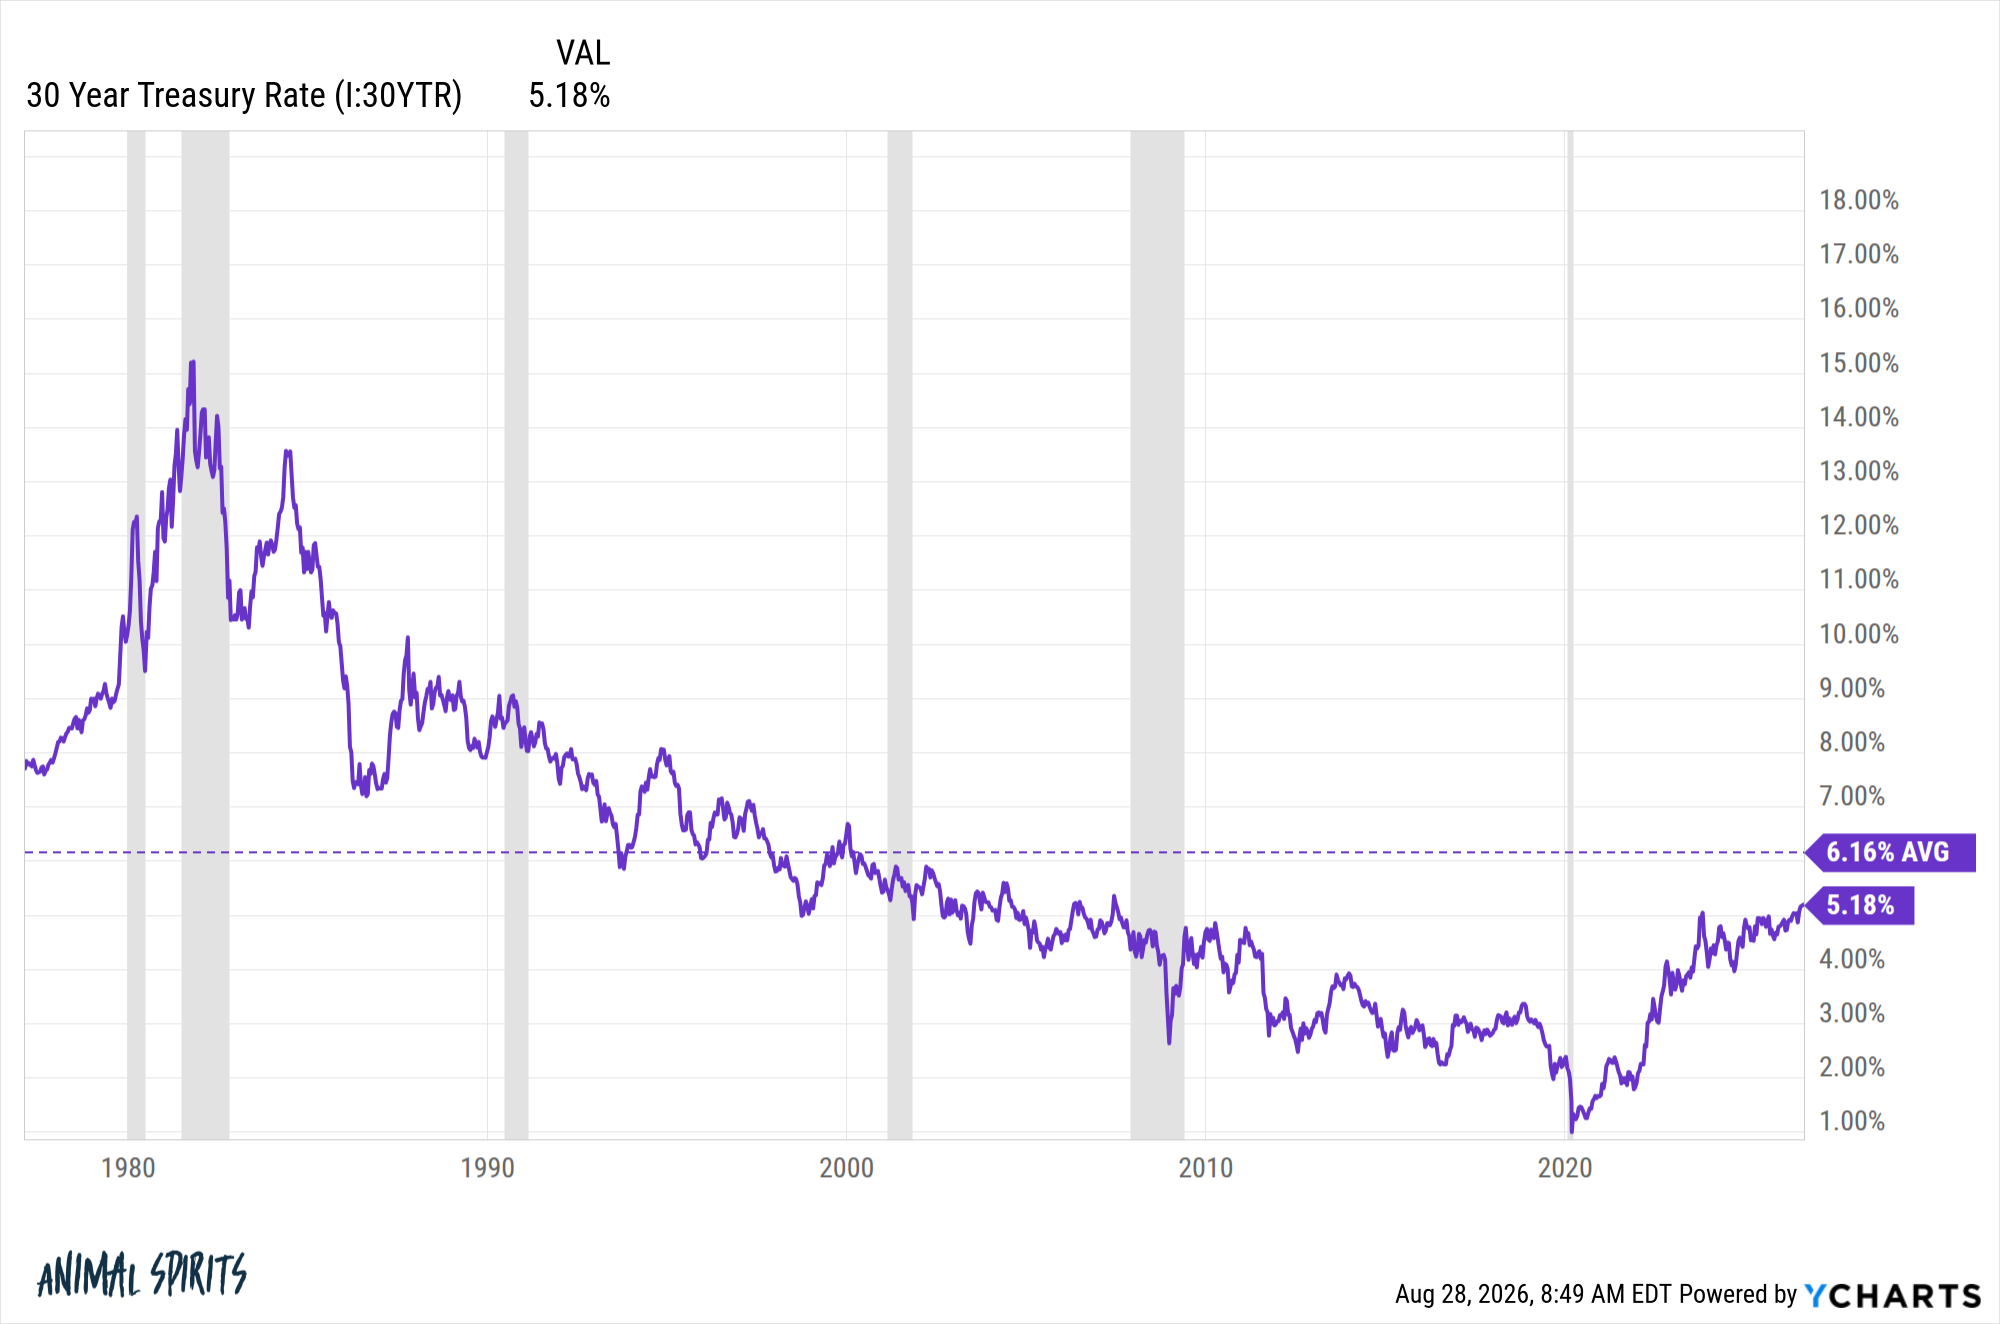
Government bond yields are dare I say…normal?
The spread between long-term and and short-term rates looks average:
Long-term bond yields are actually low relative to the past:
So what does worry me about government debt levels?
Politics.
My concern is that there are so many people worried about government debt levels but no politicians willing to do anything about it that eventually it impacts Social Security or other important government programs in a meaningful way.
Eventually there is going to be a politician that uses government debt levels as a scare tactic to gain voters and attention.
This political worry extends to government agencies trying to control the markets. Instead of focusing on policies that would help bring inflation down, Scott Bessant is trying to buyback Treasury bonds to bring rates down.
I agree with Stanley Druckenmiller Claude that you can’t fight the bond market:
I have spent five decades trading on a simple premise: Markets aggregate information no committee possesses, and prices are how that information reaches decision makers. The long-term Treasury yield is the most important price in the world. It is also the only fiscal disciplinarian the U.S. has left.
So I’m not worried about a financial crisis being caused by high government debt levels.
But I am worried about high government debt levels causing policy errors.
I trust the markets more than I trust the politicians.
Michael and I talked about government debt, bond buybacks and much more on this week’s Animal Spirits video:
Subscribe to The Compound so you never miss an episode.
Further Reading:
The Biggest Risk of Rising Bond Yields
Now here’s what I’ve been reading lately:
Books:
